By Glen Monroe, CFP®, Monroe Wealth Management. Reviewed 11/18/2026
Tax figures reflect 2026 federal and California rules as of October 2026.
Short answer
Gifting shares before an IPO moves their future growth out of your taxable estate while they're valued low, and you won't owe gift tax unless your lifetime gifts exceed your $15 million exemption. The trade-offs: you can only gift shares you own, early ISO gifts trigger income tax, and recipients keep your low cost basis (what you paid), so they owe more tax when they sell.
Who this is for
California employees at a private company that may go public who already own shares, either from exercising stock options or buying shares early, and whose estate could grow past the $15 million federal exemption.
Key takeaways
- The 2026 numbers. Each person can give up to $19,000 a year to as many people as they like without filing anything with the IRS, and up to $15 million over a lifetime before any gift tax is due. Gifts beyond that are taxed at rates up to 40%, and California has no gift or estate tax at all.
- You can only gift what you own. ISOs (incentive stock options) can't be given away while you're alive, and double-trigger RSUs don't become actual shares until after the IPO. That leaves shares you already hold, such as those from exercised ISOs, though gifting ISO shares within two years of grant or one year of exercise counts as a disqualifying disposition. When that happens, you lose the lower capital gains rate, and the gain at exercise is taxed as ordinary income.
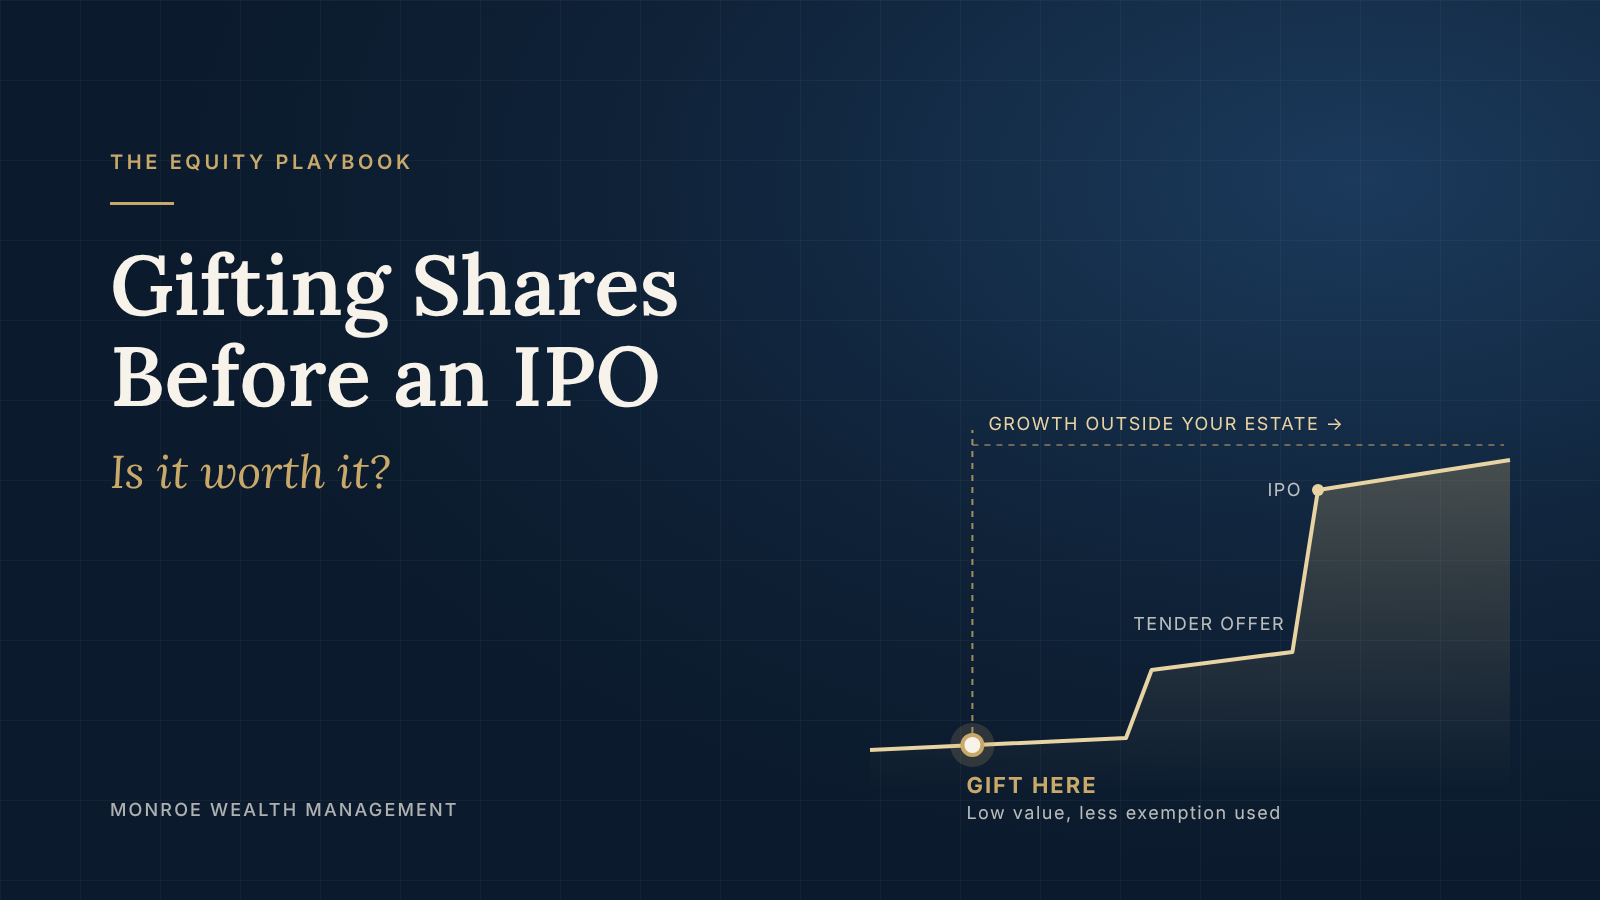
- Gifting early uses less of your exemption. A gift is valued on the day you make it, so if you expect the shares to rise, giving them while their value is low uses less of your $15 million exemption and moves all of the later growth out of your estate. That window usually closes well before IPO day, because once employees sell shares in a tender offer or investors buy in at a higher price, appraisers have to account for those prices.
- Gifting pays off for large estates. Shares you give away keep your original cost basis, while shares your heirs inherit after your death get a new basis equal to their value on the date of death, which wipes out the taxable gain. If your estate is likely to stay under $15 million ($30 million for a married couple), it won't owe estate tax anyway, so a gift saves nothing there and gives up that new basis, which can leave your family paying more capital gains tax, not less.
How it works
Gifts above $19,000 per recipient in a year (including gifts above that amount that are made by a married couple splitting gifts) are reported on Form 709, which is due April 15 of the following year. They reduce your $15 million lifetime exemption, so gift tax is owed only once your lifetime gifts pass that amount. Because the estate tax draws on the same exemption, whatever you use on gifts is no longer available to shelter your estate after your death.
What you can and can't gift
| What you hold |
Can you gift it before an IPO? |
What to know |
| Shares you own (exercised options or early-exercised stock) |
Often, if the company allows the transfer |
Private-company stock agreements can restrict transfers, so check your specific agreement first. Gifting ISO shares before you've held them two years from grant and one year from exercise costs you the lower capital gains rate, and the gain at exercise is taxed to you as ordinary income. |
| Vested NSOs (non-qualified stock options) |
Only if your stock plan allows it |
The gift only counts once the options vest, and you, not the recipient, still owe the income tax when they exercise. |
| Unexercised ISOs |
No |
Tax law doesn't allow ISOs to be transferred to anyone during your lifetime; they can only be transferred when you die. |
| RSUs, including double-trigger |
Generally no |
Most plans don't allow transfers, and double-trigger RSUs don't turn into actual shares until after an IPO. |
How the shares are valued
A gift is reported at its fair market value, which for public stock is simply the trading price. Private stock doesn't trade on public markets, so an appraiser estimates what a buyer would pay based on the company's finances, its outlook and recent sales of its stock.
Your company's 409A valuation, which is the appraisal it uses to set the exercise price on stock options, isn't built to value gifts. Reporting the gift with enough detail, which means attaching an appraisal from a qualified independent appraiser to Form 709, gives the IRS three years to challenge the value, after which it's locked in. Without that disclosure, the IRS can question the value of the gift at any time, even decades later when your estate is settled.
Recent sales carry the most weight in that appraisal, because prices from a tender offer or late-stage funding round show what buyers actually paid. Drafting a trust, getting an independent appraisal and getting the company to approve a transfer can each take months, so the planning has to start well before the next round of sales sets a higher price.
Does California have a gift tax?
California repealed its gift tax in 1982 and hasn't required an estate tax return since 2005, though a recipient who lives in California still owes state income tax on the gain when they sell.
The decisions
When is a gift worth it?
A gift is most likely to pay off when your estate is projected to exceed $15 million in 2026 ($30 million for a married couple), because that's when growth left in your estate would face estate tax at rates up to 40%. Below that amount, a gift usually saves no estate tax and still costs your heirs a new basis equal to the shares' value at your death, which for pre-IPO shares bought for pennies on the dollar can mean tax on nearly the entire gain.
Shares only get a new basis if you still hold them at death, so if you expect to sell them during your lifetime anyway, gifting them costs your family little extra, since the same low cost basis gets taxed whether you keep the shares or give them away.
We work out what your estate is likely to be worth before deciding whether to gift. If it's likely to stay under the exemption, holding the shares is often the lower-tax path for your heirs because of the step-up in cost basis when they inherit the money. If it's projected to be above the exemption, an early gift may make a material difference.
Who receives the shares
- Outright to the family. This is the simplest option, and the recipient fully controls the shares. If you give shares to children, a rule called the kiddie tax can tax much of their gain from selling the shares at your tax rate instead of their own, generally until they turn 19, or 24 if they're full-time students.
- An irrevocable grantor trust. This is a permanent trust for your family that the IRS treats as yours for income tax purposes, so you keep paying the tax on its earnings. The IRS doesn't count those tax payments as extra gifts, which lets more value build up inside the trust.
Common mistakes
- Gifting low-cost-basis stock when you could have held it for the step-up in cost basis. This is easily avoidable by understanding where you are with the estate exemption rules and whether your family could be impacted by estate taxes.
- Assuming the 0% capital gains bracket works for kids. This strategy can work, but the parents need to be aware of the kiddie tax on unearned income above a modest threshold at the parents' rate. This can be avoided by working with a professional who understands your tax and estate strategy.
- A less common mistake, but still worth calling out, is gifting shares that are underwater to help the donee get a tax write-off. Under the dual-basis rule, the recipient's basis for computing a loss is the lower of the donor's basis or the fair market value at the gift date. This isn't a practical strategy and should be avoided.
Frequently asked questions
Do I have to pay tax when I gift stock?
Usually not. The donor doesn't recognize a capital gain on the transfer, and no gift tax is owed unless lifetime gifts exceed the lifetime exemption. A gift above the annual exclusion just requires filing Form 709 and reduces the remaining exemption.
Does the person receiving the stock owe tax?
Not when they receive it. Gifts aren't income to the recipient. They pay capital gains tax only when they sell, plus tax on any dividends while they hold it.
When is the gift actually complete?
When the shares are in the recipient's account, not when you submit the transfer request. This matters for year-end gifts meant to count toward the current year's exclusion.
Talk to Monroe Wealth Management
Whether a gift makes sense depends on what your estate is likely to be worth after the IPO, how long you've held your shares and when the next tender offer or funding round could raise their value. If you'd like those numbers modeled before that window closes, book a 30-minute call with us.
Related guides
Sources
- IRS: Tax inflation adjustments for tax year 2026: $15,000,000 basic exclusion and $19,000 annual gift exclusion
- IRS Revenue Procedure 2025-32: full 2026 figures
- IRS: Frequently asked questions on gift taxes: annual exclusion per recipient, gift splitting, Form 709
- 26 U.S.C. § 2001 (govinfo): estate and gift tax rate schedule, topping out at 40%
- 26 U.S.C. § 422 (Cornell LII): ISOs must be non-transferable except by will or inheritance
- 26 U.S.C. § 424 (Cornell LII): a gift counts as a disposition of ISO and ESPP shares
- IRS Revenue Ruling 98-21: a gift of NSOs is complete only once the options vest
- Revenue Ruling 59-60 (full text): how closely held stock is valued for gift tax, including prior sales of the stock
- 26 CFR § 301.6501(c)-1 (eCFR): adequate disclosure and qualified appraisal requirements
- California State Controller: Estate tax: no California estate tax return for deaths on or after Jan. 1, 2005; gift tax applies only to gifts before June 8, 1982
- 26 U.S.C. § 1015 (Cornell LII): gifted property keeps the giver's basis
- 26 U.S.C. § 1014 (Cornell LII): inherited property gets a basis equal to value at death
- IRS Topic 553: Kiddie tax: ages and income covered
- IRS Internal Revenue Bulletin 2004-27: Revenue Ruling 2004-64, a grantor's income tax payments aren't gifts
Disclaimer
All website content, blog posts, social-media materials, case studies, calculators, illustrations, or downloadable resources are general information and not personalized investment, legal, tax, or accounting advice. Advice is rendered solely through a written agreement after completion of our client onboarding and discovery process. Do not act on information from this site without consulting a qualified professional who understands your specific circumstances.